
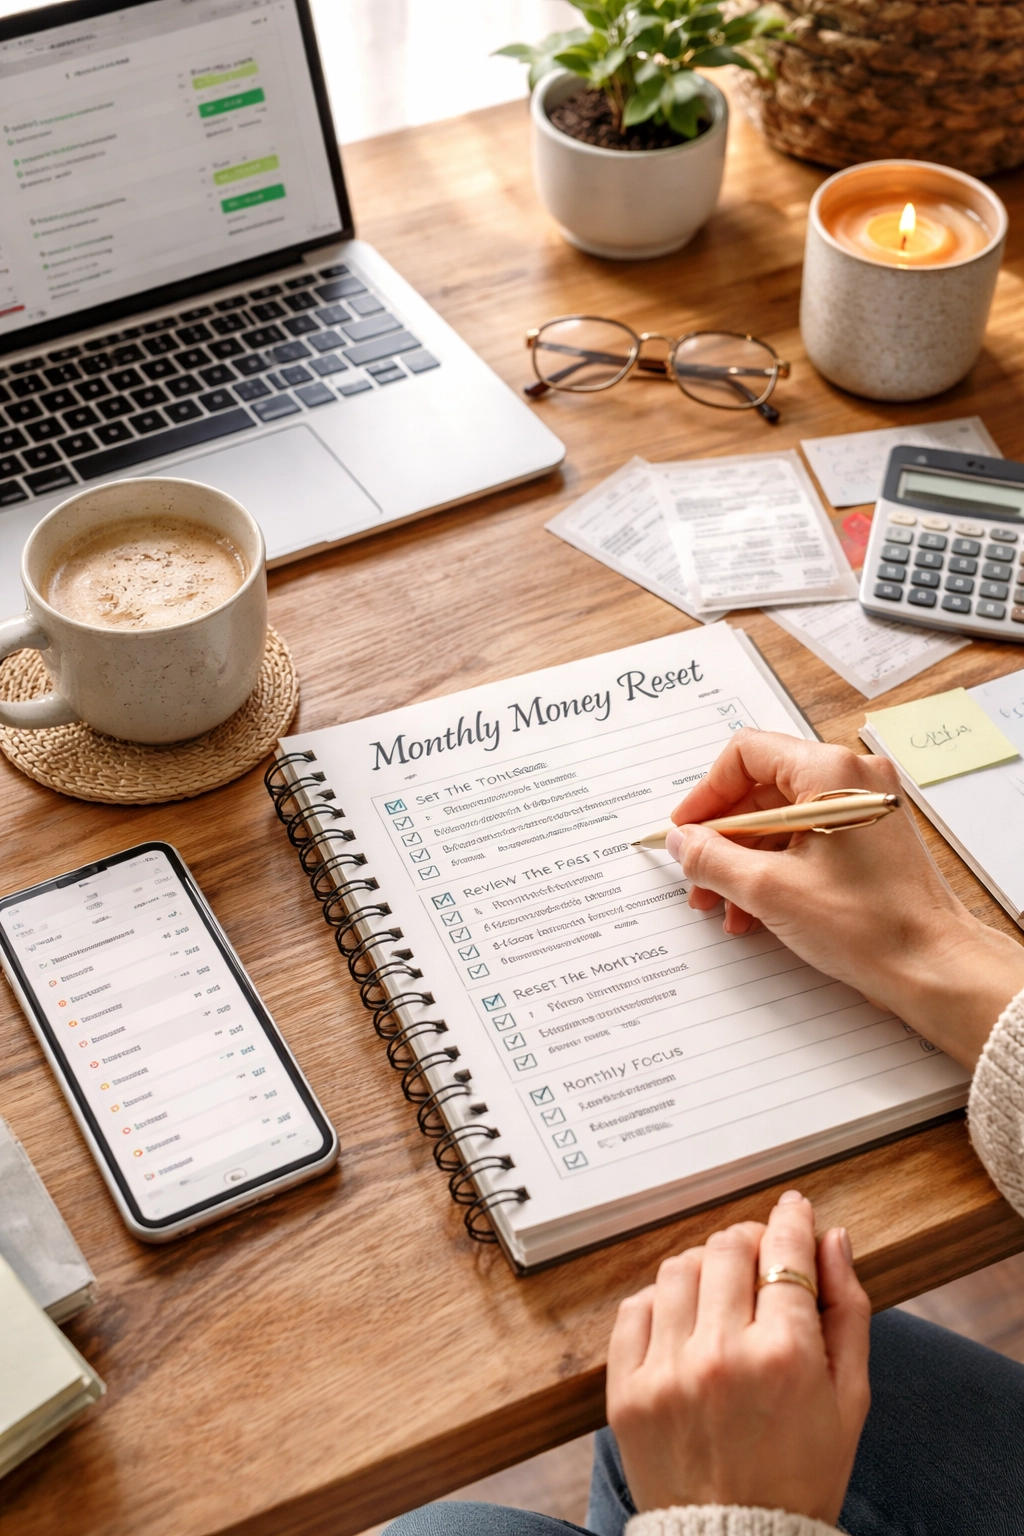
A monthly money reset is a calm, structured review of your income, spending, bills, savings and priorities. It helps you understand the month that has just ended and make a practical plan for the one ahead. You do not need a perfect budget or specialist software: your banking information, a calendar and this checklist are enough.
What is a monthly money reset?
A monthly money reset is different from writing a budget once and hoping it works. It compares your plan with what actually happened, catches upcoming costs and lets you adjust before small problems grow.
By the end of the hour, you should know:
- the current balance of your main accounts;
- where last month differed from your expectations;
- which bills and irregular expenses are approaching;
- whether your savings or debt plan needs an adjustment; and
- the single financial action that matters most next month.
Before you begin: gather these five things
- Your bank and credit-card information for the previous month.
- Your income details, including variable, freelance or benefit income where relevant.
- A list of regular bills, subscriptions, debt payments and savings transfers.
- Your calendar for birthdays, school costs, travel, renewals and appointments.
- The free monthly money reset checklist or a notebook for recording decisions.
Choose a quiet time near the end of the month, shortly before payday or on the first day of the new month. Use the same general time each month if possible, but do not abandon the routine because the date is not perfect.
The complete 60-minute monthly money reset routine
Set a timer for each stage. You are creating clarity and an action list—not solving every financial task during this hour.
minutes
1. Check your balances and recent transactions
Record the balances of your current accounts, savings, credit cards and other borrowing. Scan transactions for unfamiliar charges, duplicate payments, bank fees or refunds that have not arrived. Flag anything requiring investigation rather than becoming distracted by it now.
- Confirm that expected income arrived.
- Check that important payments cleared.
- Note any balance that needs urgent attention.
minutes
2. Review what you spent last month
Compare planned and actual spending. Look for patterns rather than criticising individual purchases. Which categories were higher or lower than expected? Was the difference caused by a genuine one-off cost, a price increase or an unrealistic budget?
- Separate essential, flexible and irregular spending.
- Identify one category that needs a more realistic amount.
- Notice spending you were genuinely glad you made as well as spending you would change.
minutes
3. Review bills, direct debits and subscriptions
Check that your regular payments are still correct and useful. Look for subscriptions you rarely use, introductory offers that have ended and services that have increased in price. Confirm that bills will leave the correct account on dates that work with your income.
Do not cancel essential insurance or protection without understanding the consequences. Add anything requiring comparison or a telephone call to a separate follow-up list.
minutes
4. Prepare for next month’s irregular expenses
Look beyond ordinary bills. Add birthdays, annual renewals, school or childcare costs, travel, celebrations, prescriptions, car expenses, home repairs and seasonal spending to your plan. If you know the annual cost, divide it into manageable contributions and consider a dedicated sinking fund.
For a longer view, use the guide to budgeting for irregular expenses.
minutes
5. Update savings and debt progress
Record what changed during the month. If possible, automate an affordable transfer shortly after income arrives. If you are paying down debt, note the current balance, interest rate, minimum payment and any planned overpayment. Keep the amount realistic enough to repeat.
You can model different repayment options with the Debt Freedom Calculator.
minutes
6. Set next month’s plan and one priority
Update your budget using the information you have just reviewed. Assign amounts for bills, essential spending, flexible spending, savings, debt and irregular costs. Then choose one clear priority.
- Build a small emergency buffer.
- Set aside money for an annual bill.
- Cancel one unused subscription.
- Reduce one flexible spending category.
- Make one manageable debt overpayment.
Schedule your next monthly reset and one brief mid-month check-in before you finish.
A realistic example
Suppose your food spending was €55 higher than planned, but €30 came from hosting family and ordinary grocery prices were also higher. Instead of imposing an unrealistic cut, you could increase next month’s food budget by €25, move €30 from entertainment and plan one lower-cost gathering. The reset turns a vague feeling of overspending into a specific adjustment.
Weekly money reset versus monthly money reset
| Weekly reset | Monthly reset |
|---|---|
| Takes around 15 minutes | Allows approximately 60 minutes |
| Checks recent transactions and immediate bills | Reviews the complete month and wider plan |
| Makes one short-term adjustment | Updates the budget, irregular costs, savings and debt |
| Keeps you aware between paydays | Prepares you for the next month |
The routines work together. Use the 15-minute weekly money reset to remain aware and this monthly review to make wider decisions.
How to do a money reset with irregular income
If your income changes each month, build the plan around money already received and essential upcoming commitments rather than an optimistic estimate. Work out a baseline covering housing, utilities, food, transport, minimum debt payments and other essentials. When income is higher, decide in advance how much will support future low-income months, irregular expenses, debt or savings.
Keep business and personal costs separate where possible, set aside any required tax and review cash flow more frequently during uncertain periods.
Only have five minutes?
A shortened reset is better than abandoning the habit. Check your available balance, the next seven days of bills, one upcoming irregular expense and the single action most likely to protect your finances. Return to the full review when you have more time.
Common monthly money reset mistakes
- Trying to fix everything at once: record follow-up work and choose one priority.
- Copying last month without reviewing it: your new plan should reflect what you learned.
- Forgetting annual and seasonal costs: scan at least one month ahead.
- Making the next budget punitive: drastic cuts often become difficult to maintain.
- Ignoring small subscriptions: review usefulness, not merely the individual price.
- Leaving without a next date: schedule the habit before closing your planner.
Download the free Monthly Money Reset Checklist
Use the printable to work through the routine, record spending observations and choose your focus for the coming month. No sign-up is required.
Monthly money reset FAQs
What is a monthly money reset?
It is a structured review of your balances, income, spending, bills, subscriptions, savings, debts and upcoming expenses. It helps you learn from the previous month and prepare a realistic plan for the next one.
When is the best time to do a monthly money reset?
Choose a repeatable time near the end of the month, shortly before payday or at the beginning of the new month. The best date is the one that gives you enough information to plan before major payments are due.
Is a monthly money reset the same as making a budget?
No. A budget assigns income to planned spending, saving and debt payments. A money reset also reviews what actually happened, checks upcoming costs and adjusts the next budget.
How often should I review my finances?
A brief weekly check supported by a more complete monthly review suits many people. Review more often when income varies, a large expense is approaching or your finances are particularly tight.
Can I complete the reset without a strict budget?
Yes. You can begin by checking balances, bills, upcoming expenses and one priority. The purpose is awareness and useful action, not enforcing a rigid budgeting method.
What if I cannot afford all my upcoming bills?
Prioritise essential costs and contact the organisations involved as early as possible. Avoid ignoring letters or missed payments. If debt is becoming difficult to manage, seek free, independent debt guidance appropriate to your country.
About Lifestyle Hub Today
Lifestyle Hub Today creates calm, practical guides, free tools and printable resources to help make everyday money decisions feel clearer and more manageable. Learn more about Lifestyle Hub Today.
Share this monthly money reset
Follow Lifestyle Hub Today
Find practical money guides, free tools and realistic everyday inspiration.
