
A suitable sinking-fund expense
A car service or insurance renewal that is likely to be due in six months. You know the purpose, can estimate the cost and have a likely date.
Turn Christmas, car costs, school expenses and annual bills into smaller, manageable amounts using a realistic sinking-fund plan.
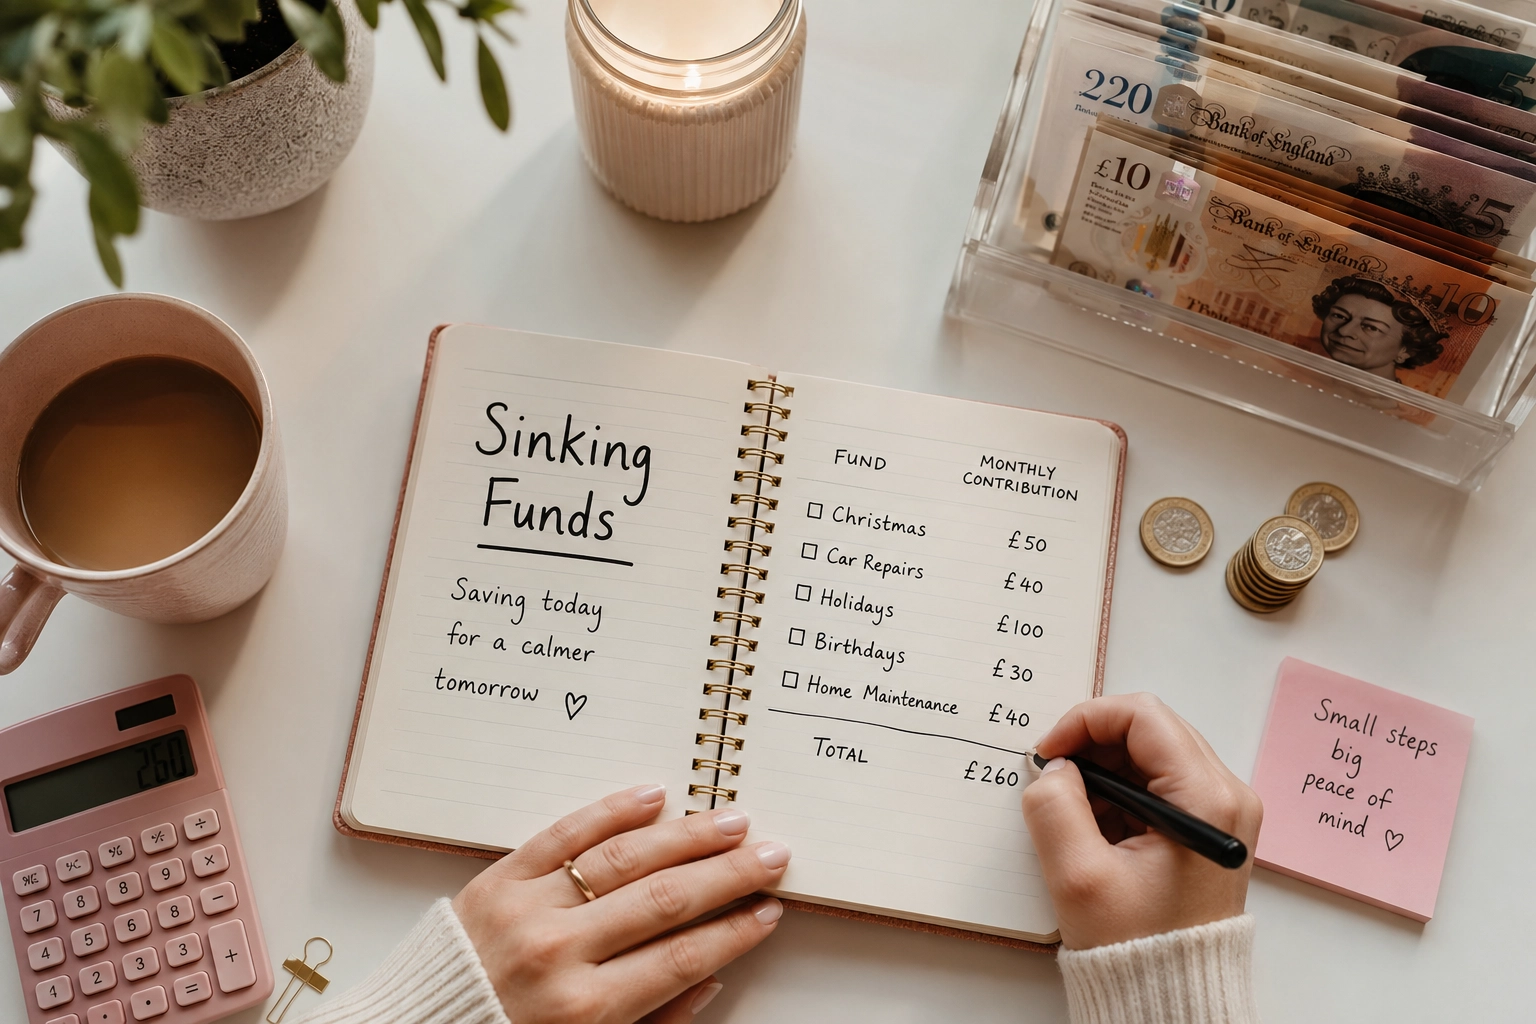
A large expense does not have to be unexpected to disrupt your budget. You may know that the car needs servicing, Christmas will arrive in December and an annual renewal is due, yet finding the full amount in one month can still be difficult.
A sinking fund closes that gap. You choose a known or reasonably predictable cost, estimate when the money will be needed and save a manageable amount towards it. This guide explains the calculation, helps you prioritise useful categories and shows where tax, account access and deposit protection may affect your choice.
In household budgeting, a sinking fund is a dedicated savings pot for a known or reasonably predictable future cost. The name can sound technical, but the principle is simple: save smaller amounts over time so the full cost does not have to come from one payday.
The same term can be used by businesses, property managers and organisations for future liabilities or major works. This guide covers only personal and household sinking funds.
A car service or insurance renewal that is likely to be due in six months. You know the purpose, can estimate the cost and have a likely date.
An urgent essential cost or income shock you could not reasonably predict and that the ordinary monthly budget cannot safely absorb.
Start with the target amount, subtract anything already saved and divide the remainder by the number of paydays, weeks, fortnights or months left.
Calculation example: You have set a £600 or €600 target for a yearly car-related cost in ten months and already have £100 or €100 saved. The remaining £500 or €500 divided by ten months gives a contribution of £50 or €50 per month.
If the calculated amount is not affordable, the result is still useful. Prioritise a more urgent cost, reduce a flexible target, extend the timeline or begin with a smaller contribution. Do not make housing, food, utilities, essential transport or priority payments difficult in order to meet a future savings target.
| Illustrative expense | Example target | Time available | Calculated amount |
|---|---|---|---|
| Christmas costs | £600 / €600 | 12 months | £50 / €50 monthly |
| MOT or NCT, servicing and tyres | £480 / €480 | 12 months | £40 / €40 monthly |
| School clothing and supplies | £360 / €360 | 9 months | £40 / €40 monthly |
| Annual insurance payment | £720 / €720 | 12 months | £60 / €60 monthly |
| Short break or family visit | £900 / €900 | 10 months | £90 / €90 monthly |
These figures demonstrate the formula. They are not typical prices, recommendations or market estimates for Ireland or the UK. Use your own renewal notices, quotes and recent spending.
Enter your own target, savings and remaining periods. The calculator works in your browser and does not send or save the figures you enter.
This is an illustrative budgeting calculation, not a savings recommendation or personalised financial advice. Check the inputs before moving money or making commitments.
Review the previous 12 months of statements, calendars and renewal emails to find costs that happen outside ordinary monthly spending. You do not need a separate pot for every possible expense.
MOT or NCT, servicing, tyres, tax, insurance excesses and annual travel passes.
Boiler servicing, planned maintenance, appliance replacement, decorating and moving costs.
Christmas, birthdays, weddings, school clothing, supplies and family visits.
Insurance, memberships, licences, subscriptions and professional fees.
Planned dental, optical, veterinary or other known costs not covered elsewhere.
Holidays, hobbies, events, technology and other optional planned purchases.
Prioritise contributions in this order, adapting it to your circumstances:
The money should remain identifiable, secure and available by the date you expect to spend it. Options may include a dedicated savings account, named savings pots within a banking app, a credit-union account or one account supported by a reliable spreadsheet that records each goal.
Before choosing an account, check access or notice rules, fees, minimum balances, interest conditions and whether the provider is covered by the relevant deposit-protection scheme. If several brands share one banking licence or institution, their balances may be combined when protection is calculated.
The Central Bank of Ireland states that its Deposit Guarantee Scheme protects eligible deposits up to €100,000 per person, per institution. Revenue states that Deposit Interest Retention Tax is generally deducted at 33% from interest paid on deposit accounts held by Irish-resident individuals, subject to exemptions and individual circumstances.
The FSCS standard deposit-protection limit is £120,000 per eligible person, per authorised firm, effective from 1 December 2025. UK tax on savings interest depends on factors including other income, tax band, available allowances and account type; qualifying ISA interest is treated differently.
Account access, interest, tax and protection rules can change. Confirm current terms with the provider and current official guidance before relying on a rate, allowance or protection limit. Sources checked 4 September 2026.
| Feature | Sinking fund | Emergency fund |
|---|---|---|
| Purpose | One planned or reasonably predictable cost | An urgent, unexpected essential cost or income shock |
| Target | Based on the expected amount and date | Based on the financial buffer the household needs |
| Use | Expected to be spent on its named purpose | Reserved for a genuine emergency |
| Examples | Christmas, school costs, insurance renewal, service or MOT/NCT | Sudden income loss or an urgent essential repair |
| After use | Set the next target and refill if the cost returns | Rebuild the safety net when the budget allows |
Many households may find both types of savings useful where the budget can support them. Priority bills, expensive debt and immediate essential needs may require attention first. The complete emergency fund versus sinking fund comparison explains how to decide what to prioritise.
Ten tiny funds can be harder to manage than two or three useful priorities. Add another only when the first system feels manageable.
Renewal prices and circumstances change. Review the target when a new quote, bill or due date becomes available.
Record withdrawals and keep the allocation clear, especially when several funds share one account.
Reduce or pause contributions when necessary rather than missing priority bills to satisfy a future target.
A difficult expense can still be predictable. Identifying it accurately makes planning for the next occurrence easier.
If an optional fund is not ready, consider changing the date, scope or target rather than taking expensive credit.
It is money saved little by little for one known or reasonably predictable future expense. You choose the purpose, target, likely date and regular contribution.
There is no required number. Starting with two or three priority costs is often easier to manage than opening a long list of small pots.
They are savings contributions rather than money already spent. Including them as planned items in the monthly budget can help you prepare for the eventual expense.
Yes, if you keep a reliable record showing how much of the balance belongs to each goal. Named pots or separate accounts may be easier for some people.
That depends on debt terms, priority commitments and essential costs due soon. A small fund for an unavoidable near-term expense may reduce further borrowing, but individual debt decisions may require free independent or appropriately qualified guidance.
It can be. Irish-resident individuals generally have DIRT deducted from deposit interest, subject to exemptions and circumstances. UK treatment depends on income, tax band, available allowances and account type. Check current Revenue or GOV.UK guidance for the rules that apply to you.
Lifestyle Hub Today creates practical guides and free tools to help readers organise everyday life with greater clarity. Our Money & Finance resources focus on approachable budgeting, saving and debt information for readers in Ireland and the UK.
Learn more about Lifestyle Hub TodayHelp somebody turn a future expense into a manageable plan.
Financial information: Lifestyle Hub Today provides general educational information, not personalised financial, investment, tax, debt or legal advice. Examples and calculator results are illustrative. Rules, rates, provider terms and support differ between Ireland and the UK and can change. Consider current official information and appropriate independent or qualified guidance before making a significant financial decision.
Prepared and checked by the Lifestyle Hub Today editorial team for clarity, calculation consistency, source links and Ireland/UK relevance. This is an editorial review, not a review by a financial adviser, debt adviser, accountant or tax professional.
